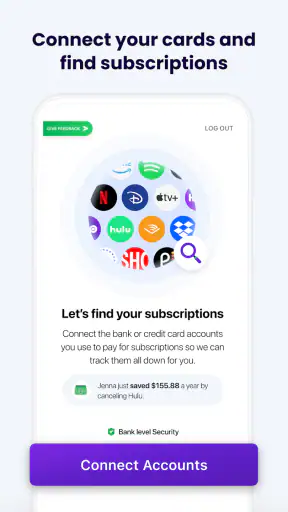
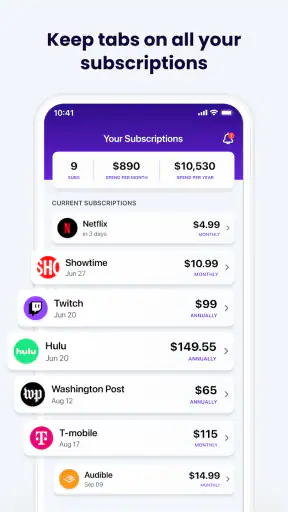
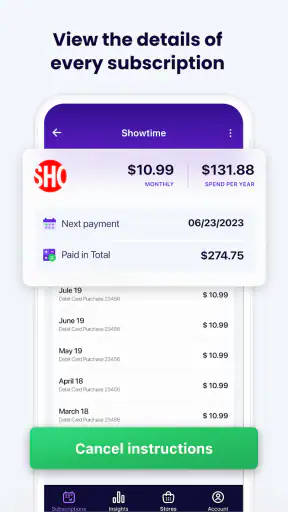
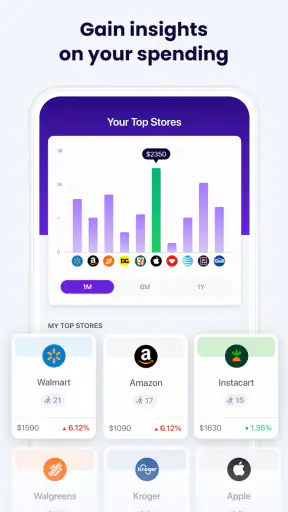
Managing subscriptions sounds simple until several small charges begin appearing at different times, under names that are not always easy to recognize. Subscription Stopper & Manager is a finance app from InMarket Media, LLC that aims to bring those recurring payments into one place and help you decide which ones should stay. I found its main appeal in the reduction of mental clutter: instead of relying on memory, scattered emails, or a bank statement checked only after money has left your account, you can use a dedicated bill-tracking and budgeting workspace.
This is a free app for Android, with optional in-app purchases ranging from $5.99 to $99.00 per item. It is rated for Everyone, runs on Android 7.0 and later, and its current version is 2.0.8. The app has passed the early-experiment stage, with over 100 thousand installs, a 3.9 average from around 3.6 thousand ratings, and roughly 2.1 thousand written reviews. Those figures suggest a useful but not universally smooth experience, which matches my impression: the idea is practical, but the value depends heavily on how carefully you review what the app shows you.
What to expect when you open the app
The first thing to understand is that this is not a replacement for your bank, card provider, or the individual services you pay for. It is better viewed as a control panel for recurring expenses. The promise is not that every subscription becomes cancellable with one tap in every situation. The useful outcome is that you become more aware of what is renewing, how those payments affect your monthly plan, and which services deserve a second look.
That distinction matters because subscription management has two separate jobs. The first is discovery: finding recurring charges that have faded into the background. The second is cancellation: ending the service through the correct company, store, or account. An app can help with the first job while still requiring you to complete the second elsewhere. I recommend treating the lists and reminders as decision support, not as proof that an account has already been closed.
The budgeting side is also more valuable when you use it for a specific purpose. Rather than entering every financial detail immediately, I would begin with recurring commitments. A monthly music plan, a cloud-storage payment, a video service, a fitness membership, and an annual software renewal can look harmless individually but become meaningful together. Seeing them as one group makes the cost easier to question.
For a first-time user, the most reassuring expectation is modest: install the app, identify your repeating charges, verify each one, and act on a single subscription you already know you no longer need. That first completed decision is more important than filling every screen on day one.
Who will get the most from it
I think the app is especially suitable for people who have accumulated digital services over several years. It can also help after changing banks or cards, moving between family plans, starting a new job, or returning from a period when spending was not closely monitored. In those moments, recurring payments are easy to overlook because they are smaller than rent, utilities, or a large one-time purchase.
It is less compelling for someone with only one or two subscriptions and an excellent personal tracking system already in place. A spreadsheet, calendar, or banking app may be enough if you reliably record renewal dates and review statements. I would also be cautious if your main expectation is automatic cancellation of every service. The app may organize the problem, but the final cancellation can still depend on where the subscription was purchased and which account controls it.
Setting up a useful view instead of rushing through it
After installation, I would resist the temptation to treat the first screen as a finished financial picture. The quality of the result depends on checking names, amounts, and renewal patterns. A recurring charge can appear under a payment processor, parent company, app-store account, or shortened merchant name, so recognition should come from comparing the entry with your own records rather than accepting every label immediately.
My preferred setup is to keep a recent bank or card statement available while reviewing the app. I look for payments that repeat, then match them with services I actually use. This simple cross-check prevents two common mistakes: overlooking a subscription because its merchant name looks unfamiliar, and assuming that a one-time purchase is recurring just because it appears in a similar category.
Once an entry looks familiar, I would add context mentally or in whatever tracking fields the app presents: the service’s purpose, the account that owns it, and whether it is paid personally or shared with someone else. Shared plans deserve special attention. A service may be worth keeping, but the person paying the bill may not be the person using it. That is a budgeting issue, not necessarily a cancellation issue.
Another useful habit is to separate “cancel soon” from “review later.” The first group should contain services you are confident you no longer want. The second can include seasonal memberships, duplicate tools, or plans that might be useful during a particular month. This avoids the all-or-nothing approach that often leads people to cancel something impulsively and then resubscribe later.
How to handle optional purchases
Because the download itself is free but the app includes optional purchases, I would pay attention to the upgrade path during setup and before confirming anything. A free entry point can be enough for someone who only wants a basic review, while a heavier subscription-management routine may justify considering paid options. The important question is not whether an upgrade exists; it is whether the additional value saves you more money or time than it costs.
I would not purchase anything simply to make the first review feel complete. Start by testing the workflow with the subscriptions you already understand. If the app helps you identify a forgotten renewal or gives you a clearer monthly picture, then you have a practical basis for deciding whether extra spending makes sense. This is particularly important in a finance app: paying for a tool should support better control, not become another recurring expense that you forget to examine.
The first meaningful success
The best first action is not entering a large number of services. It is resolving one known problem from beginning to end. For example, imagine that you signed up for a trial-based video service months ago, stopped watching it, and still see a charge on your card. Find the matching entry, verify the amount and merchant, open the appropriate cancellation route, and complete the cancellation with the provider. Then keep a note of the date or confirmation so you can check the next statement.
This workflow teaches you something important about the app’s role. It can help you locate and prioritize the expense, but the service itself remains the authority on whether the account is cancelled. If the charge continues, check whether you cancelled the correct account, whether another family member owns the plan, or whether the payment came through a different store or provider. Do not assume that removing an item from a tracker ends the underlying billing agreement.
A second realistic example is a busy household with several small plans. One person pays for storage, another pays for entertainment, and a forgotten productivity service renews annually. Instead of cancelling everything, use the app to create a conversation around the total commitment. Decide which services overlap, which are genuinely used, and which payment method should remain responsible. This is where a tracker can be more useful than a simple cancellation list: it turns isolated charges into a household decision.
After the first successful action, I would wait for the next statement before declaring victory. A cancellation can affect the next billing cycle rather than the same day, and a charge may have been authorized before the cancellation took effect. Checking the result protects you from the false confidence that comes from pressing a button without verifying the financial outcome.
Confusing entries and practical ways to sort them out
The most likely source of frustration is a mismatch between what the app displays and what you call the service. A merchant may use a legal company name, a payment intermediary, or a platform name. When an entry is unclear, compare the date, amount, and frequency with your card statement and search your email for receipts. That three-part check is more reliable than judging the label alone.
Annual subscriptions create another blind spot. A monthly budget can look healthy while an annual renewal arrives as a large, unexpected charge. I would review the tracker with two views in mind: what repeats during an ordinary month and what may return once a year. Put annual renewals on a calendar even if the app already displays them, because a second reminder gives you time to decide before the charge arrives.
Trials also need careful handling. A trial is not the same as a free service; it is usually a decision with a deadline. When you start one, record why you wanted it and what would make it worth paying for. If you cannot name that condition, treat the trial as a cancellation candidate before renewal. This approach makes the app a planning tool rather than a place where unwanted charges are discovered afterward.
Another point of confusion is the difference between a subscription and an installment. A repeating payment does not automatically mean you can cancel it like a streaming plan. Financing agreements, insurance, memberships, and service contracts can have different rules. Use the app to flag the payment, but read the provider’s terms before taking action. The safest workflow is to distinguish “recurring expense” from “freely cancellable subscription.”
Comparing it with familiar alternatives
A bank app is usually better for confirming the actual transaction because it is connected to the account that was charged. It may also offer alerts, but it can be less focused on the question of which services should be kept. Subscription Stopper & Manager is more specialized in organizing that conversation and turning recurring costs into a review task.
A spreadsheet offers more flexibility. You can add custom columns for renewal dates, household ownership, cancellation confirmation, and the reason for keeping a service. It also avoids learning a new interface. The trade-off is that a spreadsheet depends entirely on your discipline: if you forget to enter a charge, the sheet cannot discover it for you.
Calendar reminders are excellent for annual renewals and trial deadlines, but they do not provide the same financial grouping. A budgeting app may show recurring spending as part of a larger plan, which is useful when you want to manage groceries, transport, debt, and subscriptions together. This app makes more sense when the immediate problem is subscription visibility rather than a complete household budget.
In my view, the strongest approach may be a combination: use this app to find and prioritize recurring expenses, your bank app to verify charges, and a calendar to remember cancellation or renewal dates. That is not a weakness. Financial control often works better when discovery, confirmation, and reminders are handled separately instead of expecting one tool to do everything perfectly.
Privacy, accuracy, and the habit that makes the app worthwhile
Any finance-related tool deserves a slower setup than a casual entertainment app. Before entering sensitive information or connecting anything, read the screens carefully and make sure you understand what you are agreeing to. I would also avoid reviewing subscriptions while distracted, because an incorrect merchant match can lead to a missed renewal or an unnecessary cancellation.
Accuracy improves when you revisit the list after major changes. If you switch cards, join a family plan, cancel a service directly, or start a new trial, update your own records promptly. A tracker becomes stale when it is treated as a one-time cleanup project. A short review once a month is more useful than a long session once a year, especially when your spending changes often.
There is also a psychological benefit to reviewing the reason behind each payment. Ask whether the service saves time, supports work, entertains the household, or simply survived because cancellation was inconvenient. That question helps distinguish a valuable recurring expense from a forgotten one. It also reduces the chance of cutting useful services just because they appear in a list.
Who should skip it and what to do next
I would skip this app if you already know every recurring payment, check your statements consistently, and have no difficulty cancelling services through their original providers. In that situation, another finance tool may offer more value by covering broader spending categories. I would also skip it if you want a fully automated financial adviser or expect it to settle disputes with merchants. Those needs belong with your bank, card issuer, or the provider that billed you.
For everyone else, the next step is straightforward. Install it, review a small group of recurring charges, and choose one entry that you can verify without guessing. Decide whether to keep it, investigate it, or cancel it through the correct channel. Then confirm the result on your next statement. That sequence gives you a concrete success without forcing you to reorganize your entire financial life at once.
My overall impression is that Subscription Stopper & Manager works best as a focused checkpoint between your bank statement and your everyday budget. It is not a magic button for every recurring payment, and the occasional ambiguity around merchant names or cancellation responsibility means you still need to think. But for a first-time user who wants a calmer way to uncover forgotten subscriptions, its free starting point and dedicated purpose make it worth trying. The real payoff comes when the app leads to a verified decision, not merely a longer list of expenses.


